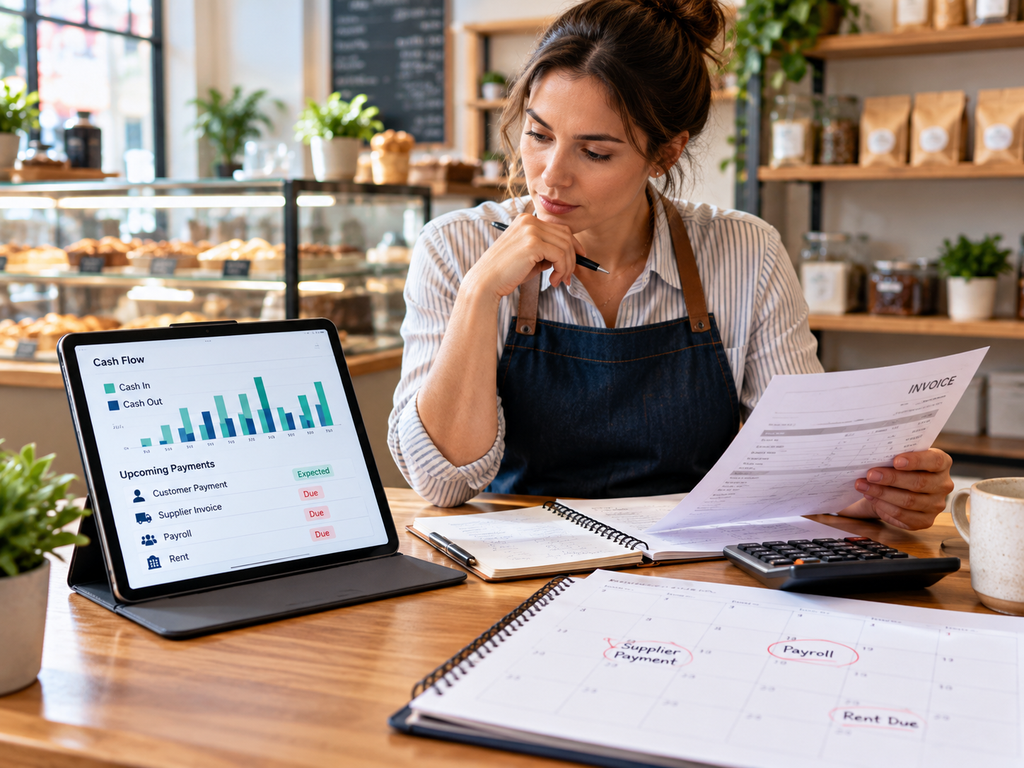
Picture a business that looks healthy on paper. Sales are steady, the calendar is full, and revenue is coming in. Then a supplier invoice or payroll date arrives before customer payments have actually landed in the account. That gap between money owed and money available is exactly what small business cash flow management is meant to address. Cash flow is significantly about timing, when money enters the business and when it has to go back out, not simply how much you’re earning overall.
Why Cash Flow Matters for Small Businesses
Healthy cash flow keeps the everyday parts of running a business moving. Payroll needs to go out on schedule, supplier invoices need to be paid, rent and subscriptions keep coming due, and taxes and loan payments don’t wait for a slow month. Inventory and other operating costs add to the list.
It helps to separate three things that often get blurred together: revenue, profit, and available cash. A business can be profitable on its income statement while still not having enough cash sitting in the account to cover this week’s obligations. That’s why an owner needs visibility into both what’s currently in the bank and what’s coming due, not just how the business is performing overall. Good cash flow management doesn’t eliminate every tight month, but it gives you a much clearer picture of what’s ahead.
Common Causes of Cash Flow Problems
Cash flow problems rarely come from one single issue. Slow-paying customers are one of the most frequent culprits, but irregular or seasonal revenue can create the same squeeze. Unplanned purchases, rising operating costs, and holding too much inventory all tie up cash that could otherwise cover near-term expenses. Growing quickly without enough working capital behind it, paying taxes or suppliers at an inconvenient time, and working from incomplete or outdated financial records can all compound the issue further.
Late Customer Payments
There’s often a real gap between finishing a job and actually getting paid for it, and that gap is where a lot of cash flow strain begins. Sending accurate invoices promptly, setting clear payment terms upfront, and tracking due dates all help narrow that gap. Following up consistently on outstanding balances and reviewing overdue accounts on a regular basis keeps things from slipping too far behind. None of this guarantees every invoice gets paid on time, but it does reduce how often you’re caught off guard.
Unexpected Business Expenses
Equipment breaks, insurance premiums shift, suppliers raise prices, and seasonal costs show up when you least expect them. These expenses are rarely predictable individually, but having visibility into your recurring obligations makes it easier to see where an unplanned cost will actually hit. Where circumstances allow, setting aside a reasonable buffer gives you some room to absorb these moments without scrambling.
Practical Ways to Improve Cash Flow
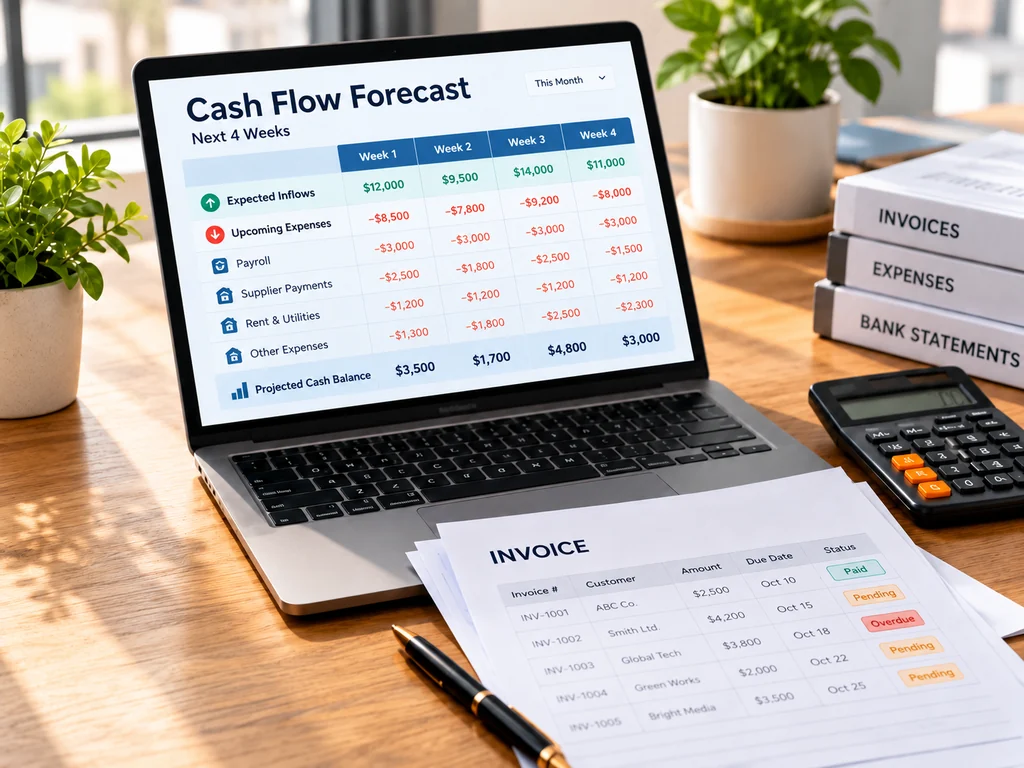
A few consistent habits make a real difference over time. Preparing short-term cash projections, even simple ones, helps you see what’s coming before it arrives. Reviewing receivables regularly and scheduling bills around expected income both reduce surprises. It also helps to separate essential spending from optional purchases, keep an eye on recurring subscriptions, and periodically review supplier terms to see if anything has changed in your favor.
Planning ahead for tax obligations rather than treating them as a once-a-year shock, building a modest emergency reserve, and avoiding unnecessary stock accumulation all support the same goal. Anyone searching for ways to improve cash flow small business owners can realistically use should start with these fundamentals rather than more complicated strategies. Forecasts and plans are only useful if they’re updated when circumstances change, so revisiting them regularly matters as much as creating them in the first place.
None of this means cutting spending indiscriminately. Learning to manage business expenses well means looking closely at what’s essential to daily operations before trimming anything, since cutting a service you actually rely on can create more problems than it solves.
How Bookkeeping Helps You Monitor Cash Flow
Current, accurate bookkeeping gives you a much clearer view of what’s actually happening with your money, incoming payments, outgoing costs, overdue invoices, and account balances all in one place. Proper categorization, regular account reconciliation, and organized accounts receivable and accounts payable records turn scattered transactions into something you can actually read and act on.
A business cash flow forecast builds on this foundation. It’s worth being clear that a forecast is an estimate based on expected income and expenses, not a guaranteed prediction of what will happen. Still, having one gives you a much better sense of what’s coming than reacting to problems as they arise. Staying on top of your small business finances this way turns bookkeeping from a once-a-year chore into an ongoing source of useful information. It’s also worth remembering that bookkeeping, accounting, tax planning, and broader financial advice each serve a different purpose, they work together, but they aren’t interchangeable.
When to Consider Professional Financial Support
Certain signs suggest it might be time to bring in outside help. Books that are consistently behind, accounts that never quite reconcile, unclear customer balances, or repeated late-payment issues are common indicators. The same goes for difficulty identifying recurring costs, financial reports you don’t fully understand, or simply not having enough hours in the week to keep records current as the business grows.
Rakow & Co. offers bookkeeping services built around fixed monthly packages, supported by cloud accounting software like QuickBooks and a dedicated accountant assigned to your business. Whether you’re based in New Jersey or working remotely from elsewhere in the US, getting your books organized is often the first real step toward stronger small business cash flow management. If your records need attention or you simply want a clearer view of where your money stands, booking a discovery call is a straightforward way to start that conversation.
Frequently Asked Questions
What is cash flow management for a small business?
It means monitoring, planning, and controlling the timing of money coming into and going out of the business.
How can I improve my business cash flow?
Send invoices promptly, monitor receivables, plan expenses ahead, forecast regularly, and keep accurate financial records throughout the year.
What causes cash flow problems?
Common causes include delayed payments, seasonal income, unexpected costs, rapid growth, excess inventory, and outdated financial recordkeeping.
How often should I review business cash flow?
Regular review is recommended, though the ideal frequency depends on your transaction volume, payment cycles, and current financial circumstances.
What is a cash flow forecast?
It estimates expected cash receipts and payments over a future period to help identify possible shortages or surpluses ahead.